Croydon Mortgage Broker
Home loans, investment loans and refinancing for Croydon residents, from a broker who knows the local market

Rated 5 from 96 Reviews
Home loans, investment loans and refinancing for Croydon residents, from a broker who knows the local market
Rated 5 from 96 Reviews
Craft Financial is a Finance and Mortgage Broker serving Croydon and Melbourne's eastern suburbs. As your Croydon Mortgage Broker, we work with home buyers, property investors, and those looking to refinance, finding lending that fits your actual situation rather than a one-size-fits-all product. We have access to a broad panel of over 40 lenders across Australia, which means more options and advice that is genuinely tailored to where you are now and where you want to go. Whether you are purchasing, investing, or reviewing an existing loan, working with a broker who knows the local area can make a real difference to the outcome.
Croydon sits within the City of Maroondah in Melbourne's outer east, offering a mix of established family homes, newer developments, and strong access to public transport via the Lilydale train line. Median house prices in Croydon have shown steady growth over recent years, making it an area that attracts both owner-occupiers and investors looking for relative affordability within the eastern corridor. The suburb's proximity to Eastland Shopping Centre, Ringwood's employment hub, and quality school catchments continues to draw buyers at a range of price points. A Croydon Mortgage Broker who understands this local context can help you make more informed decisions about your lending from the outset.
Buying your first home in Croydon is a significant step, and getting the loan structure right from the start matters more than most people realise. Croydon's median house price sits in a range that can be accessible for first home buyers compared to inner Melbourne suburbs, particularly for those targeting units or townhouses along the Maroondah Highway corridor. The suburb's Lilydale line access makes it a practical choice for buyers who want space without sacrificing commute times into the CBD.
As your Croydon Mortgage Broker, we take the time to understand your income, your savings position, and your timeline before recommending anything. We help you work out what you can realistically borrow, how repayments will look across different loan structures, and whether you are eligible for government grants or stamp duty concessions that can reduce your upfront costs. The First Home Owner Grant and the First Home Guarantee scheme are two options worth exploring depending on your circumstances.
We also help first home buyers understand the difference between variable and fixed rate loans, what lenders mortgage insurance means for your deposit, and how your loan-to-value ratio affects the options available to you. These are decisions that have a long-term impact, and we make sure you understand them clearly before you commit. Our first home buyers page has more detail on what to expect through the process.
From pre-approval through to settlement, we handle the paperwork and lender communication so you can focus on finding the right property. We keep you updated at every stage and explain what is happening in plain language. Buying your first home in Croydon does not need to feel overwhelming when you have a broker in your corner who has done this many times before.
Croydon Mortgage Broker clients purchasing established homes in the suburb will find a market that has held its appeal across multiple property cycles. The area's mix of quarter-acre blocks, period homes, and newer medium-density developments gives buyers a range of entry points, with houses in established pockets of Croydon consistently attracting strong competition at auction. Proximity to Croydon train station and the Ringwood employment precinct continues to underpin demand from owner-occupiers looking for liveability and long-term value.
We work with owner-occupiers at every stage, whether you are purchasing your first home, upsizing into a larger family property, or downsizing into something more manageable. The right loan structure depends on your income, your timeline, and your longer-term goals, and we take all of that into account before recommending anything. We help you weigh up variable versus fixed rate options, understand offset accounts and redraw facilities, and choose a loan that gives you flexibility as your circumstances change.
As your broker in Croydon, we manage the full application process from start to finish. That includes preparing your file, submitting to the lender, responding to any conditions, and keeping you informed right through to settlement. You will not be chasing us for updates or trying to work out what is happening next. Our home loans page covers the types of products and structures we work with in more detail.
Once your loan settles, we do not disappear. We review your lending regularly to make sure the rate and structure still work for you, and we will flag any opportunities to reprice or restructure before they become issues. That ongoing relationship is something we take seriously for every Croydon home loan client we work with.
For property investors in Croydon, getting the loan structure right is just as important as choosing the right property. Croydon continues to attract investors drawn to its relative affordability within Melbourne's eastern corridor, with rental demand supported by families, young professionals, and students accessing the Lilydale line. Gross rental yields in Croydon have remained competitive compared to inner-ring suburbs, and the area's ongoing infrastructure investment along the Maroondah Highway corridor adds to its medium-term appeal.
A Croydon Mortgage Broker who understands investor lending can save you time, money, and a significant amount of frustration. We work with a lot of self-employed borrowers and investors who have complex income structures, multiple properties, or trust and company setups that require a more considered approach to the application. Getting the structure wrong at the start can limit your ability to grow your portfolio later, which is why we look at each loan in the context of your broader position.
We consider interest-only versus principal and interest repayments, how lenders assess rental income and business income, and how to position your borrowing so future purchases remain achievable. Whether you are acquiring your first investment property or adding to an existing portfolio, we help you move forward with clarity rather than guesswork. Our investment loans page has more detail on how we approach investor lending.
We also work closely with accountants and buyers agents who know the Croydon and eastern suburbs market, and where it adds value, we can connect you with the right people at the right time. The goal is to make sure every part of your investment strategy is working together, not just the loan itself.
If you have held your loan for a few years and have not reviewed it recently, there is a reasonable chance you are paying more than you need to. Refinancing in Croydon is one of the most practical ways to reduce your repayments, access equity for a renovation or next purchase, or consolidate existing debt into a more manageable structure. With Croydon property values having grown steadily over recent years, many owners are sitting on more usable equity than they realise.
As your Croydon Mortgage Broker, we review your current loan, compare it against what is available across our lender panel, and give you an honest assessment of whether switching makes sense. We look at the full picture, including any break costs, discharge fees, or cashback offers that might affect the numbers. If refinancing stacks up, we manage the entire process. If it does not, we will tell you that clearly and explain why.
Refinancing is also worth considering if your circumstances have changed since you took out your original loan. A change in income, a new investment property, or a shift in your goals can all mean your current loan structure is no longer the right fit. We help you work through those scenarios and find a structure that reflects where you are now. Our refinancing page covers the process in more detail.
We also work with borrowers across nearby suburbs, including Ringwood North, Ferntree Gully, Montrose, and Boronia. Whatever your situation, Craft Financial is here to help you make informed decisions about your lending. Book a time to chat and we will take it from there.

Working with a Croydon Mortgage Broker through Craft Financial means you have a clear process from the first conversation through to settlement and beyond. Here is how we work with you.
We start with a conversation to understand your goals, your income, your current setup, and where you want to head. At this stage, we also collect the key documents we need so we can move quickly and avoid delays later. This first conversation is about understanding your short-term plans as well as your longer-term goals, so we can map out the right path forward for your Croydon purchase or refinance.
Once we have the full picture, your Croydon Mortgage Broker puts together lending strategies tailored to your situation. We show you what you can borrow, how repayments look across different structures, and which lenders are the right fit. The focus is not just on this loan, but on how it positions you for future opportunities. Where it adds value, we can also connect you with trusted accountants, buyers agents, and conveyancers who know the Croydon and eastern suburbs market.
When you are ready to proceed, we take care of the paperwork and deal directly with the lender on your behalf. Our team handles the heavy lifting while keeping you updated at every step, so the process is clear and straightforward from start to finish.
We work to secure the right outcome for you, whether that is pre-approval, a refinance, or settlement on your new property. We guide you right through to the finish line, explaining everything along the way so you are never left wondering what happens next.
Your Croydon Mortgage Broker does not disappear after the loan settles. We keep reviewing and repricing your loans so you are never paying more than you should. We check in regularly to make sure your setup still works as your life and goals evolve, and when you need specialists around you, we can connect you with the right people at the right time.
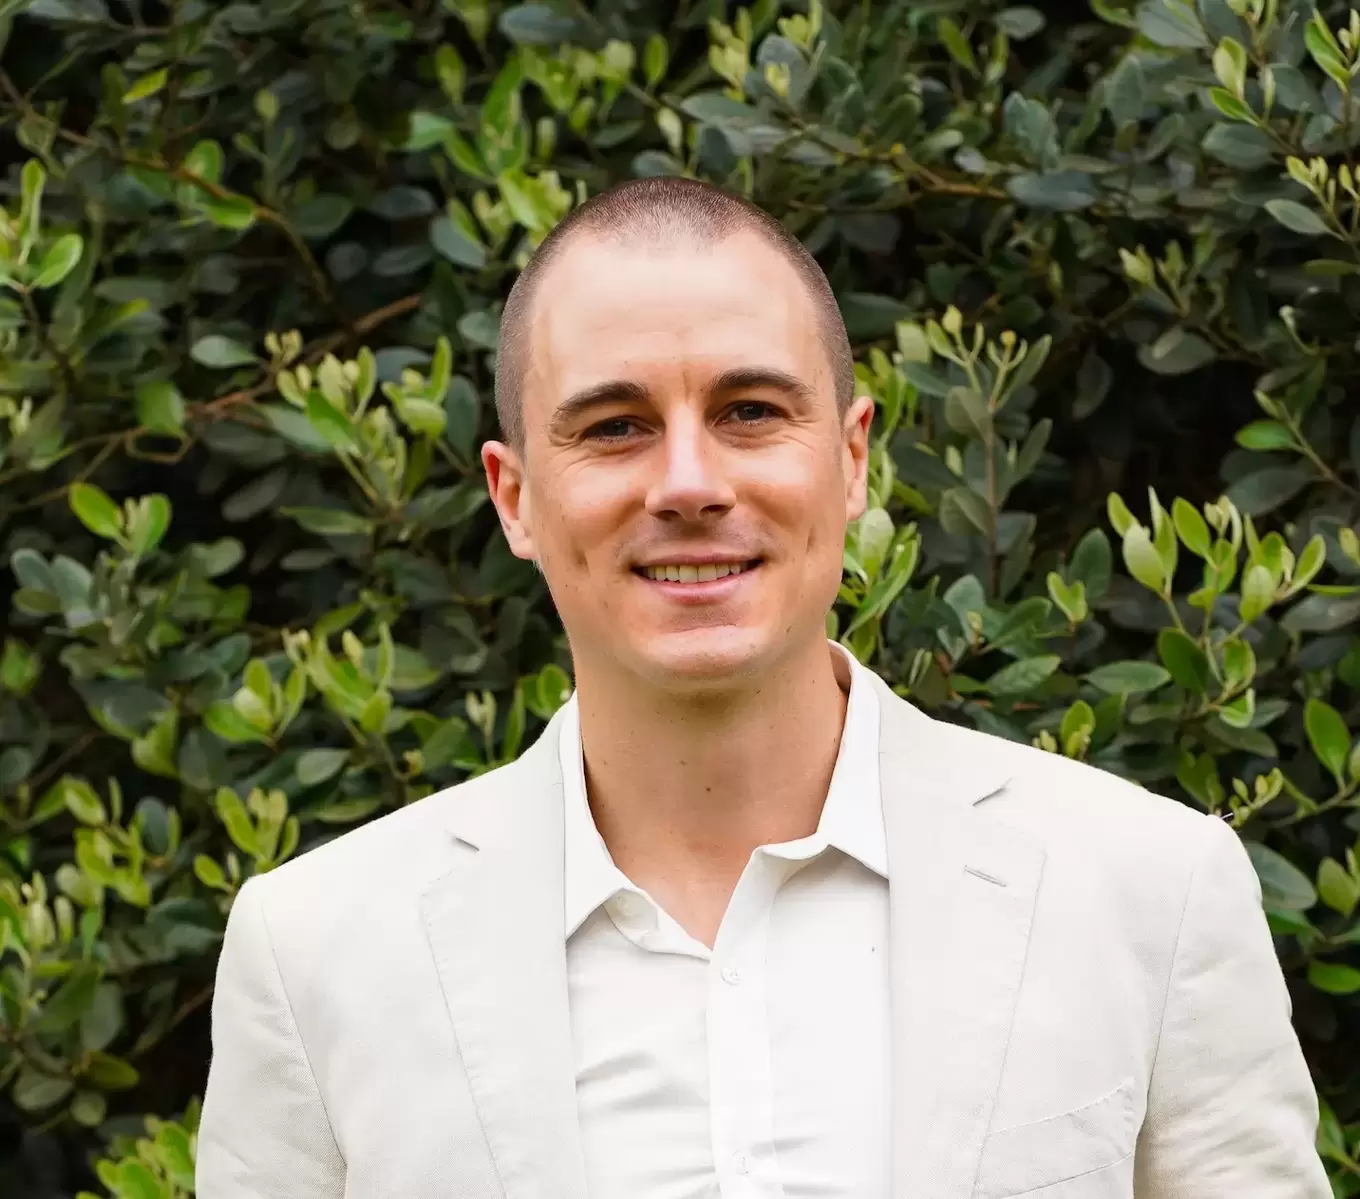
Craft Financial is led by Tom Carmody, a Finance and Mortgage Broker who works with home buyers, property investors, and those looking to refinance across Croydon and Melbourne's eastern suburbs in Victoria. Tom and the team are available seven days a week and take a genuine client-first approach to every conversation, from the first enquiry through to long after settlement.
Tom has a strong understanding of the Croydon property market, including the types of properties available across the suburb's established pockets and newer medium-density developments, how lenders view the area, and what buyers and investors are working with at different price points. Croydon's position within the City of Maroondah, its Lilydale line access, and its proximity to Ringwood's employment and retail hub all factor into how lending decisions are made in this part of Victoria. That local knowledge, combined with hands-on experience across a wide range of lending scenarios, means Tom is well-placed to give advice grounded in what is actually happening in Croydon right now.
He is particularly experienced working with self-employed borrowers and property investors who have complex income structures, trust or company setups, or multi-property portfolios. These situations require more than a standard application, and as your Croydon Mortgage Broker, Tom takes the time to understand the full picture before recommending a path forward.
As MFAA members, Craft Financial works with a broad panel of lenders across Australia, giving Croydon residents access to home loan, investment loan, refinancing and construction loan options rather than being limited to a single bank or product suite.
From your first conversation through to settlement and beyond, we handle the paperwork, manage lender communication, and keep you informed at every stage. Once your loan settles, we continue reviewing your lending regularly to make sure you are never paying more than you should. Craft Financial is not just your broker for this transaction. We are a long-term finance partner as your property goals and circumstances evolve in Croydon and across Victoria.
Book AppointmentSS
Samuel Sassoon
Buying my first house with Tom was an absolute breeze. He made the whole process seamless and stress free. Was available at all times to answer my questions regardless of how stupid they are. Had issues with an ANZ branch and not only did he personally go into the branch to get it resolved, he also spoke directly with his contacts in ANZ. If you’re looking for anything finance related go no further than Tom and the team at craft financial they are the best in the business
AP
Andrew Portelli
Thomas is great explained everything step-by-step and what's involved it was an easy transition moving brokers
MS
Matt Stringer
Had a really good experience. Very thorough and transparent. Genuinely really helpful.
We arrange finance for a wide range of investment property types across Australia. This includes residential houses, units, townhouses, and apartments in metropolitan and regional areas. We also have access to lenders who finance unique properties like student accommodation, dual occupancy properties, and houses with minor non-conforming features. Whether you're purchasing established properties or off-the-plan developments, we can structure appropriate finance solutions. Some lenders have restrictions on certain property types or locations, but our extensive panel ensures we can usually find suitable options. We also help with commercial property purchases when they form part of your investment strategy, connecting you with specialist commercial lenders when required.
As specialists in working with self-employed property investors, we understand the unique challenges you face when securing finance. Traditional lenders often struggle to assess self-employed income, which can make the mortgage application process more complex. Our team has extensive experience working with various income structures including sole traders, partnerships, companies, and trusts. We know which lenders are most receptive to self-employed borrowers and how to present your financial position in the most favourable light. This specialised knowledge means we can often secure finance when others cannot, helping you build your property portfolio without unnecessary delays or rejections.
The documentation requirements vary depending on your business structure and the lender's requirements. Generally, you'll need two years of tax returns including notices of assessment, recent business activity statements, and bank statements for both personal and business accounts. If you operate through a company or trust, we'll need financial statements and company documents. For your investment property, you'll need a contract of sale, rental appraisal, and property valuations. We provide you with a comprehensive checklist tailored to your specific situation and help you gather everything efficiently. Our team reviews your documents before submission to ensure they present your application in the strongest possible manner to lenders.
Our assessment process looks beyond traditional employment income to understand your complete financial picture. We examine your tax returns, business activity statements, bank statements, and cash flow patterns to determine your genuine borrowing capacity. For self-employed clients, we consider factors like business consistency, industry trends, and seasonal variations in income. We also look at your existing property portfolio, rental income potential, and investment strategy. This comprehensive approach often reveals borrowing capacity that traditional assessments might miss, allowing you to maximise your investment opportunities while ensuring the loans remain serviceable within your financial circumstances.
Our mortgage broking services are typically funded through commissions paid by lenders, which means most clients don't pay direct fees for our standard services. However, for complex applications requiring significant additional work, or for certain specialised services, we may charge professional fees. These are always discussed and agreed upon upfront before any work commences. We believe in complete transparency about costs, so you'll always know exactly what you're paying for any services. Our focus is on providing value through our expertise and securing finance outcomes that justify any costs involved. Most clients find that the benefits we deliver through loan structuring and lender selection far outweigh any fees charged.
A declined application doesn't mean the end of your property investment plans. Our extensive lender panel means we often have alternative options when one lender says no. Different lenders have varying appetite for self-employed borrowers and different assessment criteria, so a decline from one doesn't predict outcomes with others. We analyse the reasons for any decline and adjust our approach accordingly, whether that means presenting information differently, choosing alternative lenders, or addressing specific concerns raised. Sometimes a decline indicates we need to strengthen your application by improving documentation or waiting for better financial results. We work with you to understand what's needed and develop a plan to achieve your financing goals, even if it takes longer than initially expected.
Absolutely. Refinancing can be an excellent strategy for property investors to improve cash flow, access equity, or secure more favourable loan terms. We regularly help self-employed investors refinance their portfolios to take advantage of changing market conditions or their improved financial position. The process involves reviewing your current loans, assessing your financial situation, and identifying opportunities for improvement. This might include consolidating multiple loans, switching to interest-only payments, or accessing equity for your next purchase. We handle the entire refinancing process including valuations, legal documentation, and settlement coordination, ensuring minimal disruption to your investment strategy while maximising the financial benefits.
Portfolio structuring is one of our key strengths when working with property investors. We help you optimise your loan structure across multiple properties to maximise tax benefits, maintain flexibility, and prepare for future growth. This might involve using different loan products for different properties, structuring cross-collateralised facilities, or keeping properties in separate loan accounts for easier management. We consider factors like your entity structure, tax position, and future investment plans when recommending portfolio arrangements. Our approach ensures your finance structure supports your long-term investment strategy rather than creating limitations. We also review existing portfolios to identify restructuring opportunities that could improve your position or unlock additional borrowing capacity.
The timeframe varies depending on several factors including the complexity of your financial situation, the lender chosen, and how quickly documentation is provided. For self-employed borrowers, the process typically takes 4-6 weeks from application to approval, though this can be longer during busy periods or if additional information is requested. Pre-approval can often be obtained within 1-2 weeks, which is valuable when making property offers. We work to expedite the process wherever possible by ensuring applications are complete and accurate from the start. Our established relationships with lenders often help speed up the assessment process, and we keep you informed of progress throughout to manage expectations and ensure smooth settlements.


Craft Financial Pty Ltd ABN: 20 687 355 817. Credit Representative #533831 is authorised under Australian Credit Licence #389328.
Disclaimer: This page provides general information only and has been prepared without taking into account your objectives, financial situation or needs. We recommend that you consider whether it is appropriate for your circumstances and your full financial situation will need to be reviewed prior to acceptance of any offer or product. It does not constitute legal, tax or financial advice and you should always seek professional advice in relation to your individual circumstances.
Site by Broker Studio